Here’s the P+L:
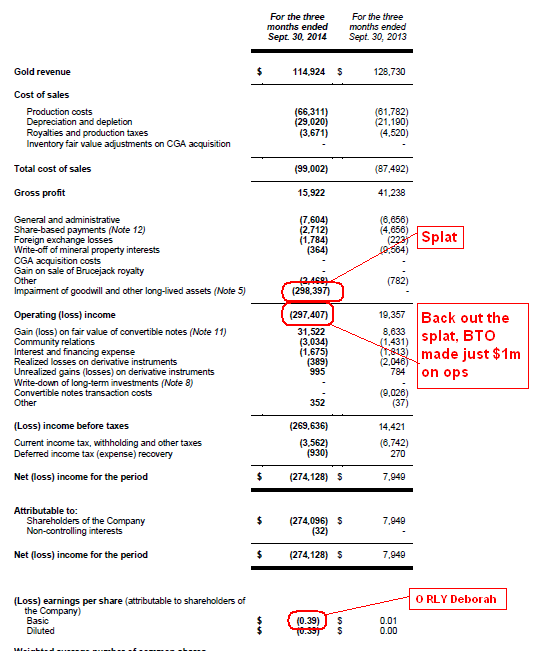
Oh, looky that, a 39c EPS loss on the quarter thanks to a near $300m hit on goodwill from Masbate ($202m) and Gramalote ($96m). Which looks bad, but it might not be all the kitchen sink yet either. For those who care, once you throw in Papillon the new balance sheet puts P/BV at U$2.55, so with bTG closing at U$1.58 this evening either there’s more write downs to come or the market is underpricing BTO bigtime. Or both, as maybe the truth lies somewhere between the two (my best guess).