Further to yesterday’s post on Cardinal Resources (CDV.to) that pointed out how the company was paying A$935k per quarter in interest expenses on a U$25m loan priced at LIBOR +7.75% (plus the $2m or so in ‘transaction fees’ at the front end), your humble scribe’s eyes were pointed by a couple of readers toward the latest CDV corporate presentation and, in particular, the slides noting the economic modelling they use to try and sell your their company. Example this one, slide 9:
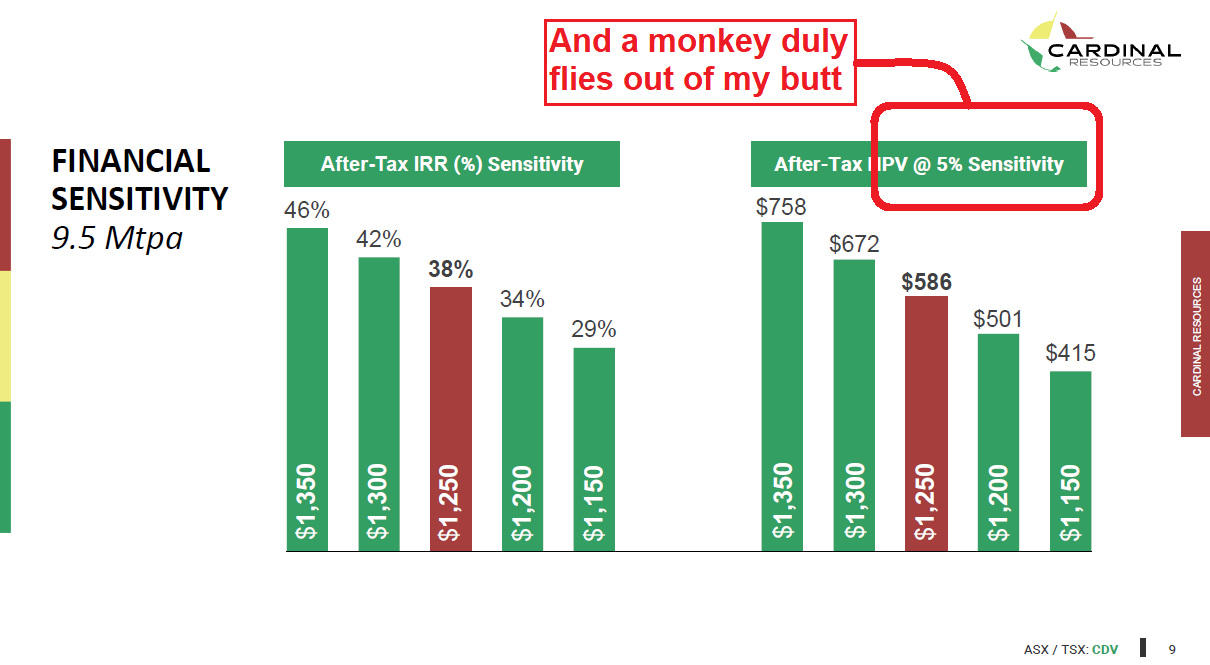
At what point does it stop being simple corporate BS of the highest order to pretend a cost of capital of 5%, when the real cost for this company to raise money on a gold mine project in West Africa is multiples higher? At what point can you accuse these people of full-blooded fraudulent activity? I’d say we’re pretty close here, as the real cost of capital at CDV is obviously North of 15%. I mean, even the company’s own literature and economic modelling states at a 10% discount rate the NPV at U$1,250/oz gold (their benchmark number) drops by U$210m (to U$376m). What would a 17% rate do for those numbers above? But no, even after a 2018 PFS on the project using a range of economic criteria and after all the evidence you could ever need that assuming 5% is codswallop, CDV just ploughs ahead in its 2019 corporate presentation and makes believe to a naive world that its project is worth far more than the truth.
By simple logic and by following the trail of clearly marked numbers at CDV, we can state that CDV pays and will pay way more than that imaginary 5% discount rate for its capital. Best guess me at 15% and frankly, that’s being generous. However, the CDV management and board have decided not to advertise the numbers that the real rate they pay would do to their project and, by consequence, share price. They are hiding the truth from you, which is just another way of writing the bottom line to this post; They are liars. Burn them with fire. Rant over.